Home / Resources / Strategy library / VWAP pullback
Strategy library · Education only
VWAP pullback: follow the trend back to the line.
On a trend day, price keeps returning toward VWAP and leaving again. The pullback strategy waits for that return and trades the turn back in the trend's direction. Here are the rules, two real MNQ sessions, and how it fits a daily loss limit.
What is a VWAP pullback strategy?
A VWAP pullback is a trend-continuation strategy. When price has spent the morning on one side of VWAP (the volume-weighted average price since the open) and VWAP itself is sloping that way, the strategy waits for price to pull back toward VWAP, then enters when price turns back in the direction of the trend. The stop goes beyond the pullback, and the target is a multiple of that risk.
It is the opposite of the better-known VWAP fade, which bets on price snapping back to VWAP after a big stretch. On a trend day, fading VWAP means standing in front of the trend; the pullback version waits for the trend to come back to you.
What VWAP is, in one line
VWAP = the sum of (price × volume) for every trade since the anchor, divided by the total volume since the anchor. Intraday
traders usually anchor it to the 9:30 ET cash open and draw bands one or two volume-weighted standard deviations
(σ) either side. Because it weights every price by the volume traded there, it is often read as the day's "average fair price".
The idea in four lines
- Trend: price has stayed on one side of VWAP for a while, and VWAP is sloping the same way.
- Pullback: price comes back to a zone near VWAP (VWAP itself, or the 1σ band between price and VWAP).
- Entry: the first close back in the trend's direction after the touch.
- Stop and target: stop beyond the pullback's extreme, target a multiple of that risk.
Every one of those words needs a number before the strategy can be tested: how long is "a while", which zone, how far back does the slope look, what time window. The full breakdown has the exact numbers we used.
Why it needs a trade cap in a prop account
The trend filter can be true for hours, so the setup can repeat. On a day where the trend gives way, every pullback entry can stop out in turn. A daily loss limit treats the third or fourth loss of the morning exactly like the first, so the number of trades per day is part of the strategy, not an afterthought.
What is in the full breakdown
- The rule cardTrend filter, zone, entry, stop, target, time window and trade cap, in numbers.
- A real green dayMNQ, 5 Aug 2026: two pullback entries, step by step.
- A real red dayMNQ, 25 Sep 2026: two stops, and why the loss stayed inside the limit.
- Prop-rule fitDaily loss limit, trailing drawdown and consistency, worked in numbers.
- A test-it-yourself planHow to backtest and stress-test it before it costs you an evaluation.
The full breakdown · free with your email
VWAP pullback: rules, real charts, prop-rule fit
Unlocked. Your link is on its way by email.
Free with your email
Read the full vwap pullback breakdown
The rule card, a real green day and a real red day on MNQ, and the two-trade cap that kept the red day small. We also email you the link, so it is one tap away next time.
1. The rule card
VWAP pullback to the 1σ band, 1-minute bars
- VWAP. Anchored at
9:30ET, with a volume-weighted ±1σ band. - Trend. The last
20one-minute closes were all on the same side of VWAP, and VWAP is further that way than it was30minutes ago. - Pullback. Price trades back to the 1σ band on the trend side (the band between price and VWAP: the lower band in a downtrend, the upper band in an uptrend).
- Entry. Within
10bars of the touch, the first close beyond the touch bar in the trend's direction, on the trend side of VWAP. Enter on that close. - Stop. The pullback's extreme: the highest high (short) or lowest low (long) from the touch bar to the entry bar.
- Target. Two times the risk (2R).
- Window and cap. Signals only from
10:00to14:30ET, and at most2trades a day. - Size. Contracts = the money you allow per trade ÷ (stop distance in points × point value), rounded down, and the cap × that risk must fit your daily limit.
We tested a VWAP fade on the same recorded sessions first; it rarely reached its target, so we do not teach it. That does
not show the pullback version is profitable either: it is the clearer worked example of the rules, which is why we walk through it. MNQ is $2 a point (CME Group contract specs); examples use 3 MNQ, so
every point is $6.
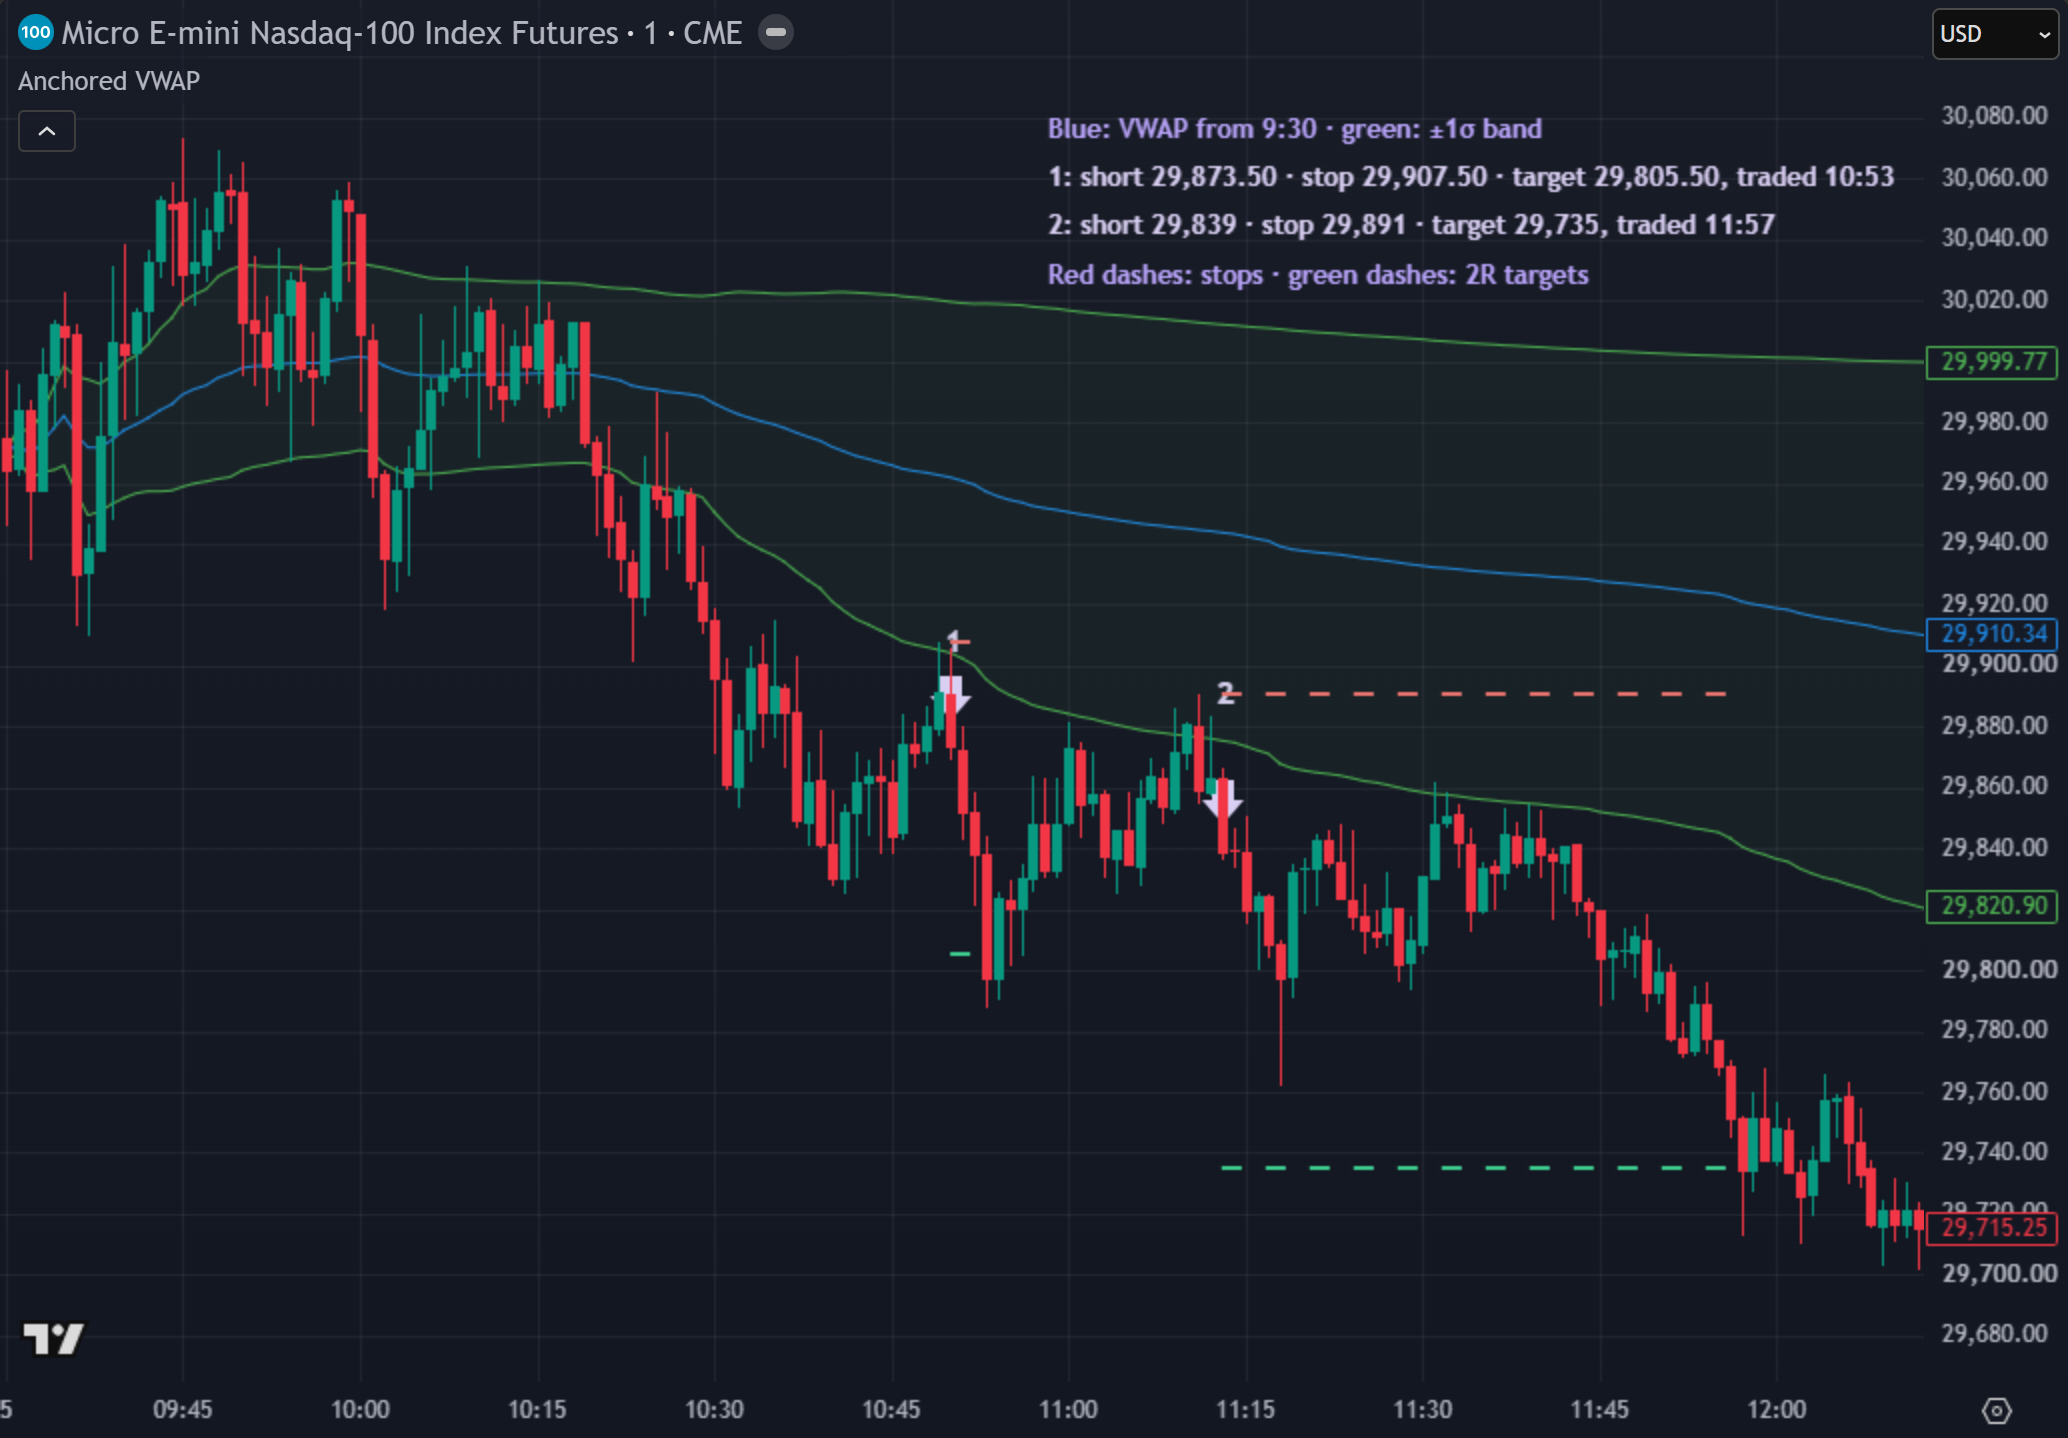
2. A day the rules worked
Real chartSelected example, chosen to show the rulesTwo targets
| Trade | What the chart shows | Risk | Outcome at 3 MNQ |
|---|---|---|---|
| 1 | Downtrend filter true. Pullback to the band, then a close back down at 10:50 (29,873.50). Stop at the pullback high 29,907.50. | 34 pts | 2R reached 10:53: 68 × $6 = +$408 |
| 2 | Second pullback, close back down at 11:13 (29,839.00). Stop 29,891.00. | 52 pts | 2R reached 11:57: 104 × $6 = +$624 |
| Day, before commissions and slippage | +$1,032 | ||
Price spent the morning under a falling VWAP. Each time it rallied back to the band, the rule waited for a bar to close back below the touch bar before entering, so the stop could sit just above that rally's high. After the second trade the cap of two ended the day, even though the trend carried on. Hypothetical: what the written rules would have done that day, not trades anyone placed (CFTC Rule 4.41 notice below the next example).
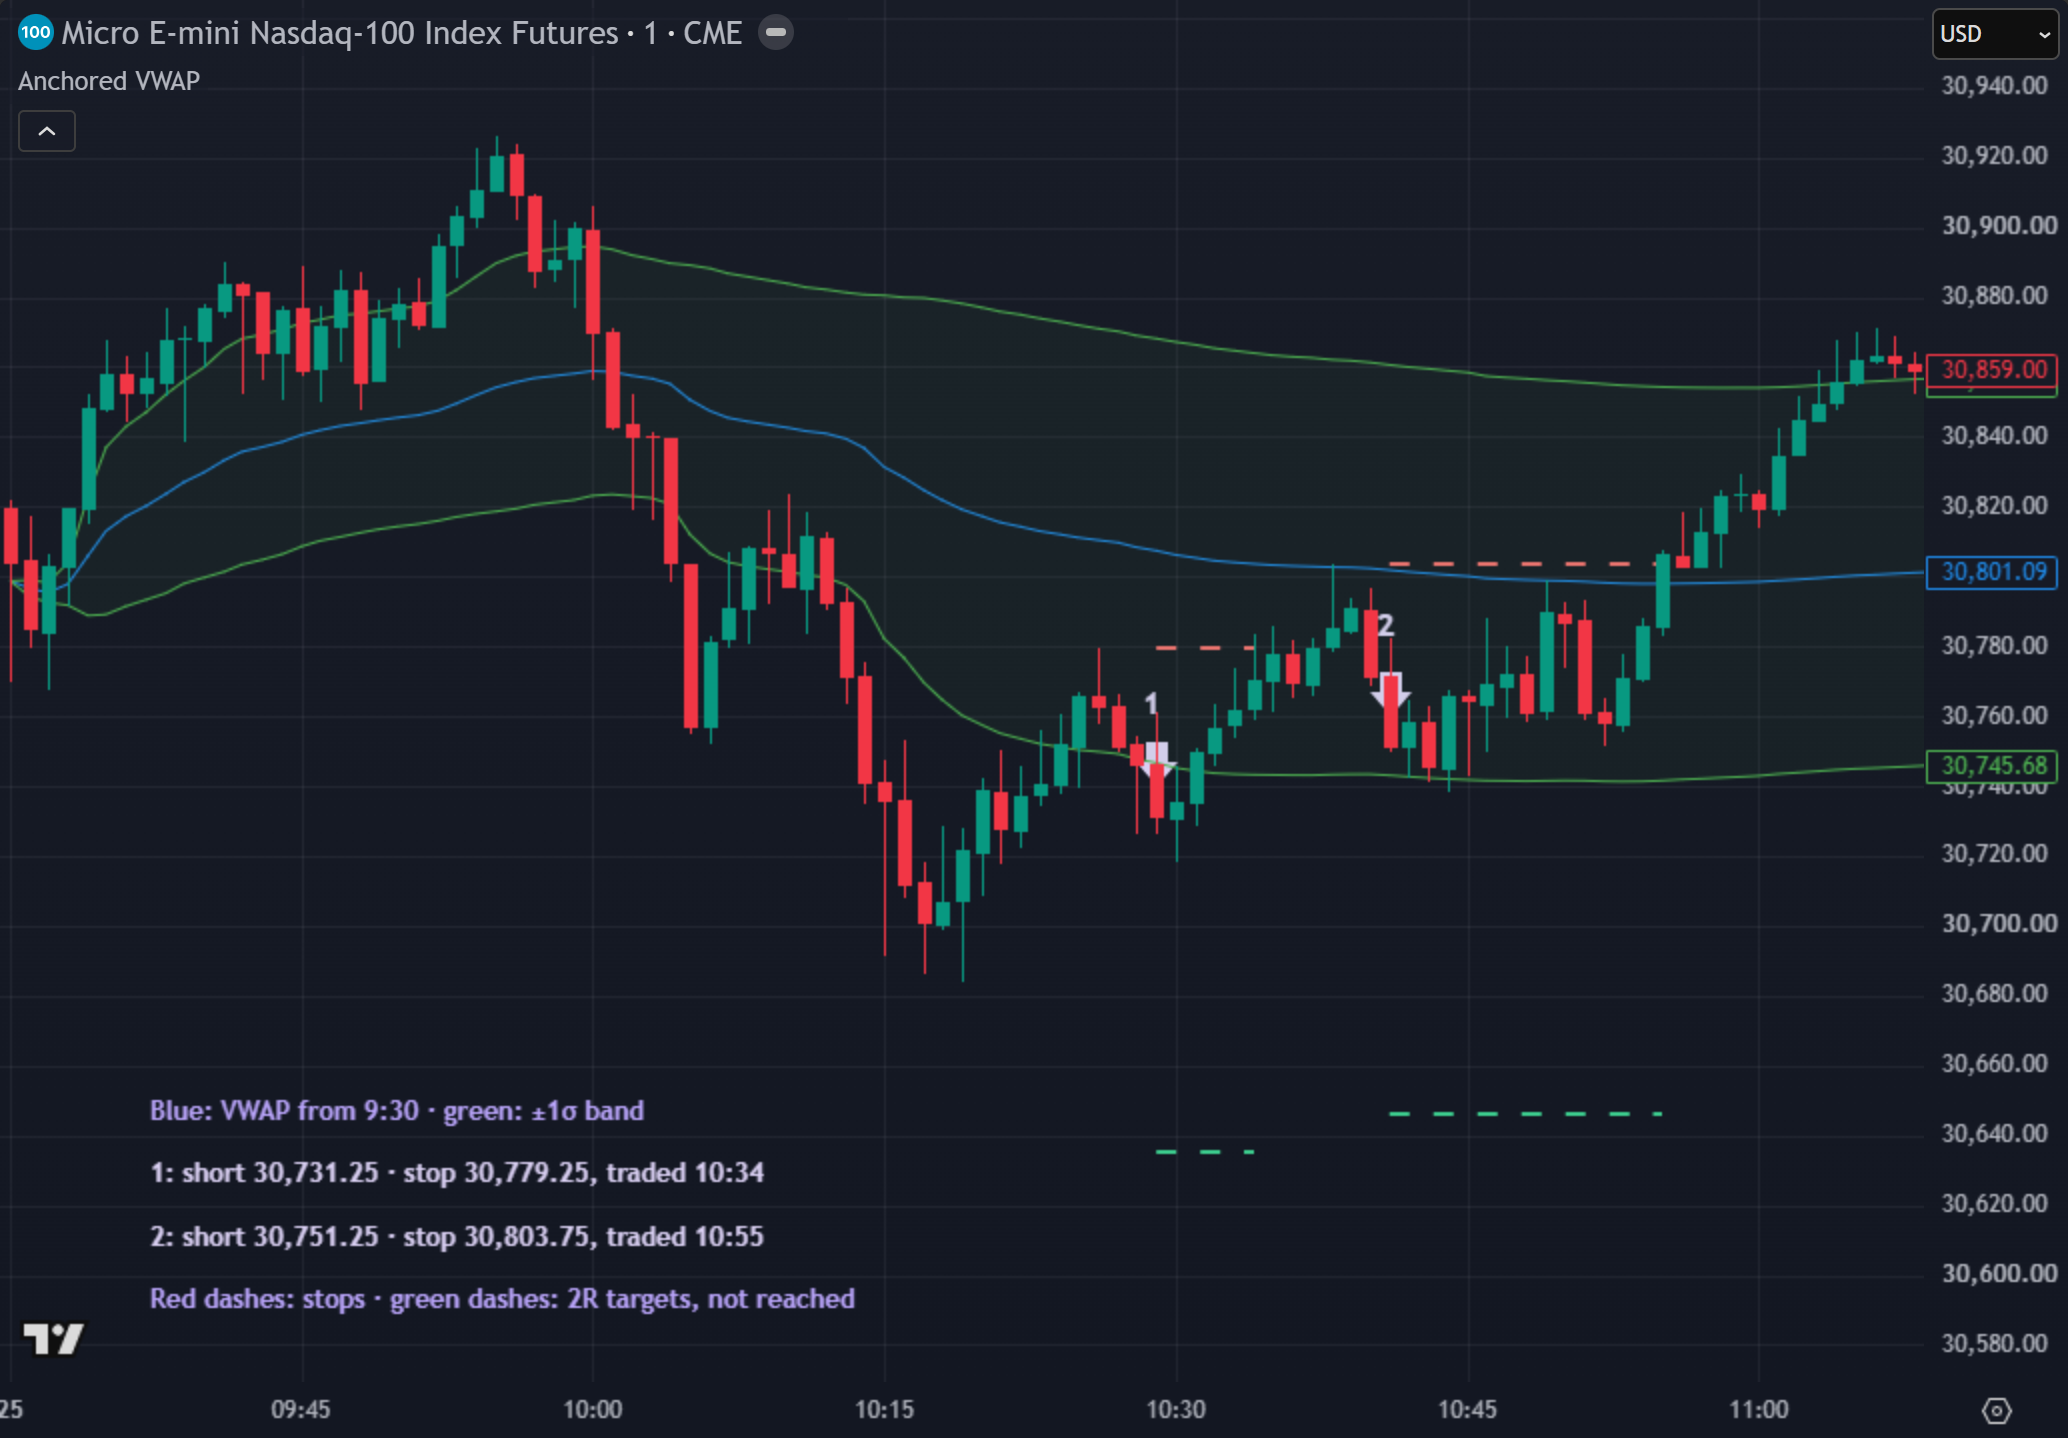
3. A day the same rules failed
Real chartSelected example, chosen to show the rulesTwo stops
| Trade | What the chart shows | Risk | Outcome at 3 MNQ |
|---|---|---|---|
| 1 | Downtrend filter true. Close back down at 10:29 (30,731.25), stop 30,779.25. | 48 pts | Stopped 10:34: −$288 |
| 2 | Close back down at 10:41 (30,751.25), stop 30,803.75. | 52.5 pts | Stopped 10:55: −$315 |
| Day, before commissions and slippage | −$603 | ||
The trend filter was true on both days; on 25 September the down-move gave way and each pullback kept going. Without a cap,
the next signal would have been a third entry into a market that had stopped trending. With the cap, the worst case was
known before the open: 2 trades × a stop of up to about 52.5 pts × $6 ≈ $630,
inside a $1,000 daily loss limit (example limit). The actual day was −$603, and the account
traded the next session.
Can you spot a 25 September in advance? In our small sample we found no filter that reliably separated the green days from the red ones, so we do not offer one. Test any filter before trusting it.
CFTC Rule 4.41: Hypothetical or simulated performance results have certain limitations. Unlike an actual performance record, simulated results do not represent actual trading. Also, since the trades have not been executed, the results may have under- or over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profit or losses similar to those shown.
4. How it fits prop firm rules
Daily loss limit: cap × risk must fit
Work backwards from the limit. Example figures: a $1,000 limit and a 2-trade cap leave $500
a trade. With a 52.5-point stop, one MNQ risks 52.5 × $2 = $105, so $500 ÷ $105 = 4.8, rounded
down to 4 MNQ. With a 34-point stop ($68 a micro) it is 7. Stops differ trade by
trade here, so size each trade from its own stop or use the largest stop you allow.
Trailing drawdown: the near-miss costs twice
Under an intraday trailing drawdown, a trade that runs toward its target and then reverses to the stop costs room twice: the
floor rose with the open profit, and the balance fell. Example figures at 3 MNQ with a 52-point stop: a
trade that reaches +90 pts open (+$540) from a new balance high and then stops out
(−$312) lifts the floor $540 and drops the balance $312, so the room left shrinks by
$852, not $312.
Consistency rule: a two-target day is a big day
Example figures: under a 50% consistency rule, a +$1,032 best day needs total profit of at least
$1,032 ÷ 0.50 = $2,064 before it fits. Rules and percentages differ by firm; check yours.
5. Test it yourself before you trade it
- Pin down every word. VWAP anchor, band width, how many closes make a trend, the slope look-back, the zone, the entry bar, the window and the cap. Change one and you have a different strategy.
- Check your VWAP matches your platform's. Session anchor, how volume is counted and the band formula differ between platforms, and so do the signals.
- Backtest on many sessions, with costs. Commission both ways and slippage on every fill. Delay can only cost: model a late fill as worse than the backtest price, never better.
- Count red days, not just trades. The cap turns a losing streak into a losing day; check the worst run of red days against your trailing drawdown.
- Forward-test it on a simulator for weeks before any paid evaluation.
Know a trader learning this strategy? Send them this breakdown. It's free for them too.
Disclosures
Education only. This page explains how a widely known, public strategy is defined and tested. It is not advice, not a recommendation to trade any contract, size or strategy, and not a signal: it shows no setup for any future session. Charts are real past sessions, chosen to show the rules (including a day they failed); they are selected examples, not typical results. The charts are TradingView snapshots (MNQ1!, one-minute, regular trading hours); the range, entry, stop and target marks and labels on them were added by Tarrow Futures. Bars may differ slightly from those on your platform. Trade outcomes on this page are what the written rules would have done on those days, before commissions and slippage. They are not trades Tarrow Futures placed. Dollar figures for sequences and rules are example figures, not results. Prop firm rules differ and change; your firm's current rulebook decides. Futures trading involves substantial risk of loss. Automation does not remove risk.
CFTC Rule 4.41: Hypothetical or simulated performance results have certain limitations. Unlike an actual performance record, simulated results do not represent actual trading. Also, since the trades have not been executed, the results may have under- or over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profit or losses similar to those shown.