Home / Resources / Strategy library / Prior-day high/low
Strategy library · Education only
Prior-day high and low: break or rejection?
Yesterday's high and low are two lines every trader can see. Some trade a close through them; others trade the poke through that closes back inside. Here is how each is defined, the rejection rules walked through on two real MNQ sessions, and why a small stop needs careful sizing in a prop account.
Unlocked. Your link is on its way by email. Jump to the full breakdown ↓
The full breakdown · free with your email
Unlock the full prior-day high/low breakdown
The rule card, two real MNQ sessions (one target, one stop) and what costs and size do to a 10-point stop. The free overview is below; we also email you the link, so it is one tap away next time.
What are the prior-day high and low?
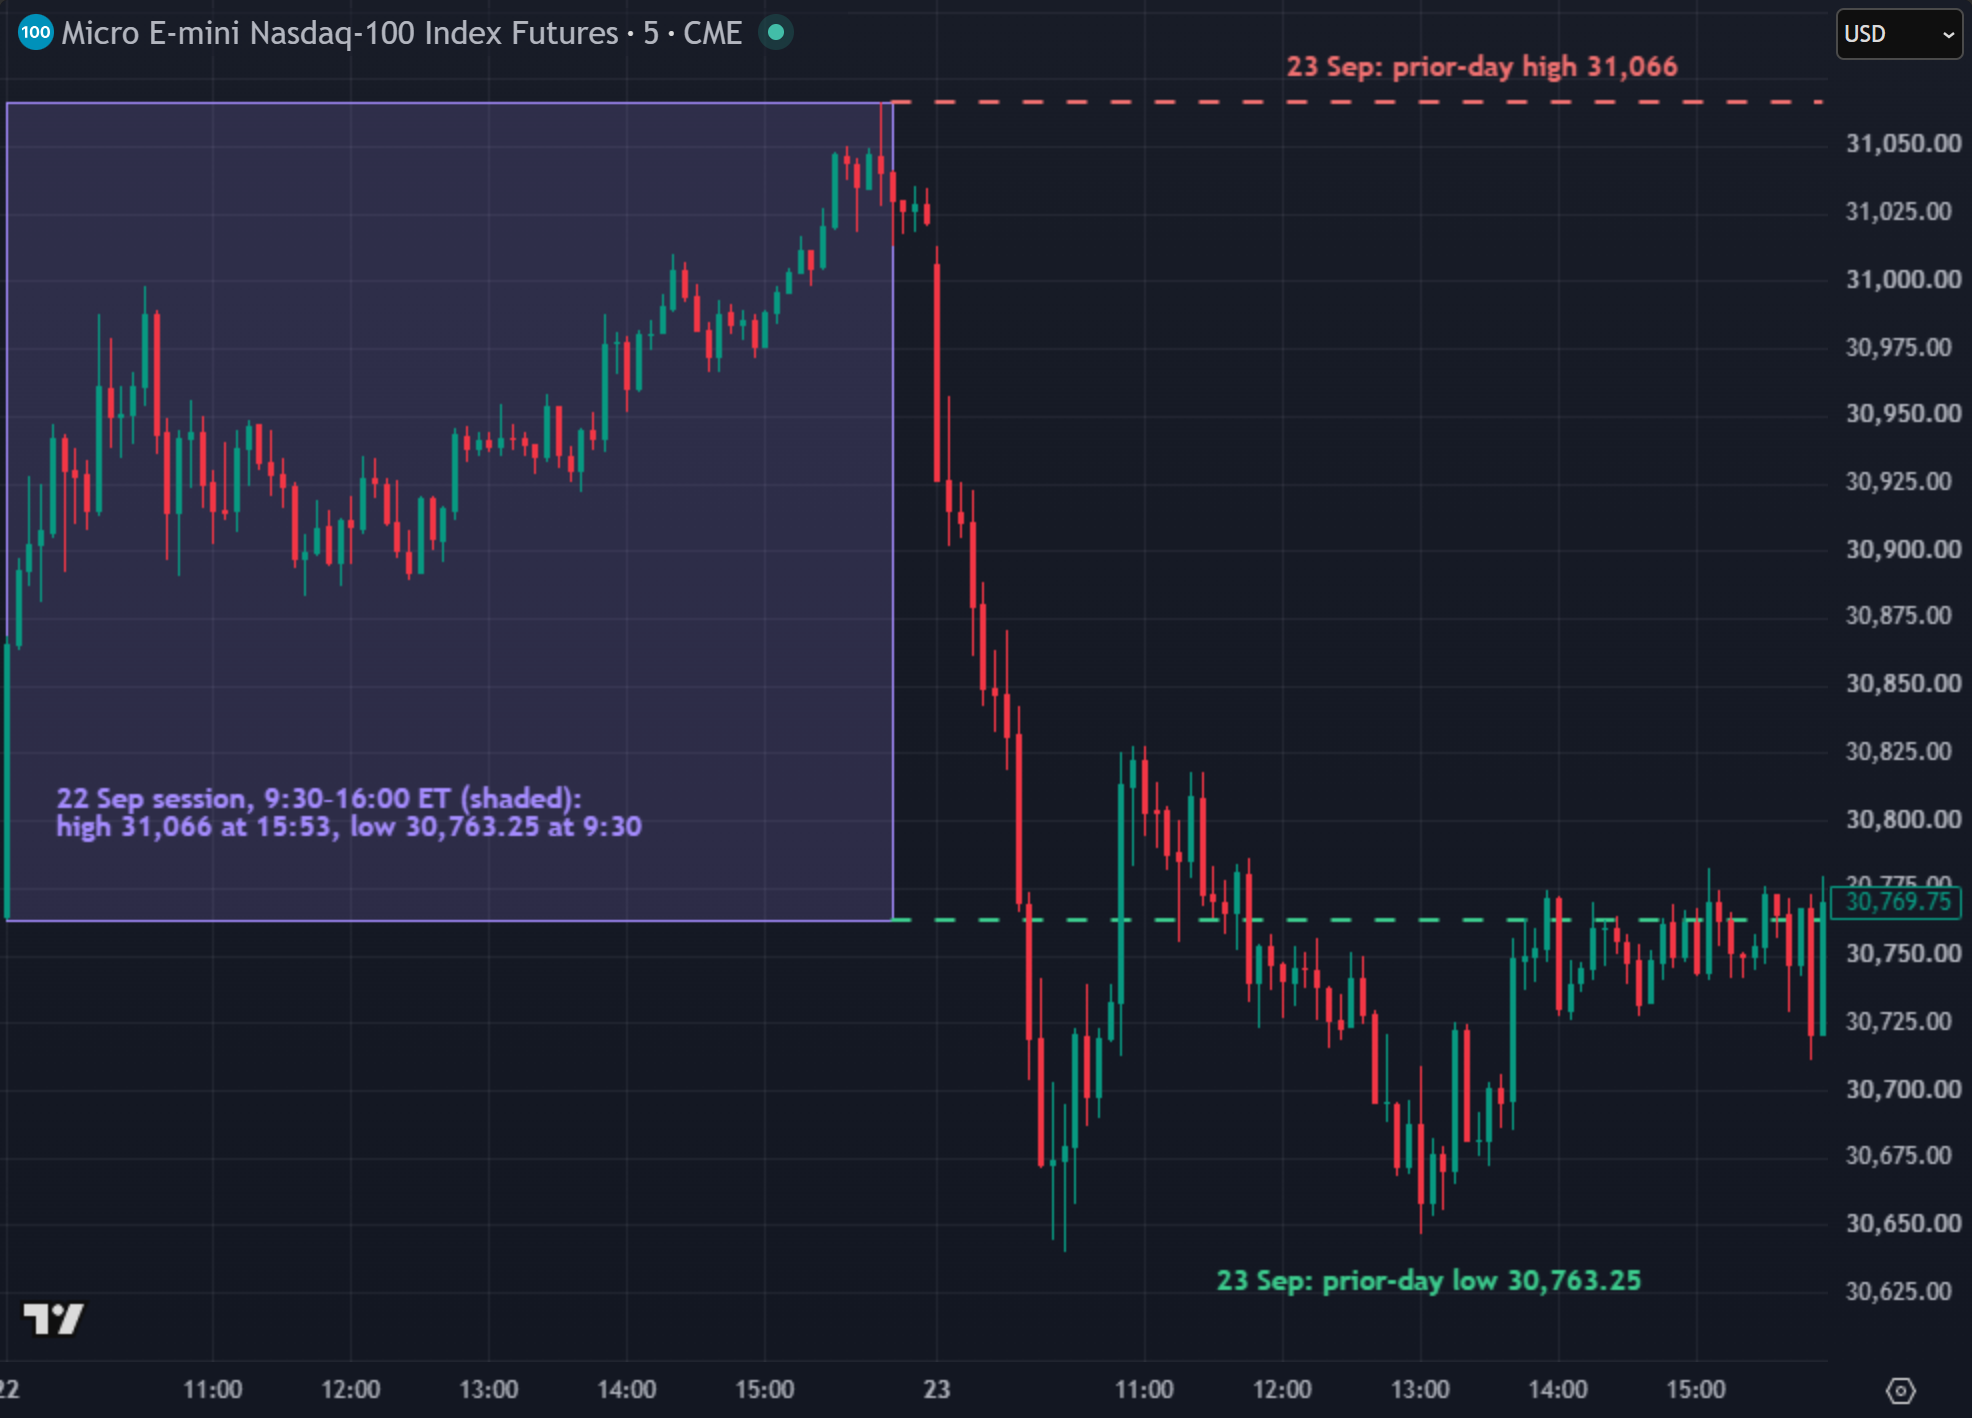
The prior-day high (PDH) and prior-day low (PDL) are the highest and lowest prices of the previous trading session. They are two of the most watched levels on an intraday chart because everyone can see them, nobody has to calculate them, and they mark where the last session's buyers and sellers stopped.
For index futures such as MNQ and NQ, "the prior day" needs a definition, because the futures trade almost around the clock.
We use the regular session, 9:30 to 16:00 ET (8:30 to 15:00 CT),
the hours of the US cash market. Some traders use the full electronic session including overnight, which gives different levels
on many days. Neither is right or wrong; pick one and write it down before you test anything.
Break or rejection: two strategies on the same two lines
Traders use the levels in two opposite ways, and it matters which one you mean:
- The break: a bar closes beyond the prior-day high (or low), and you trade in the direction of the break, expecting the move to continue.
- The rejection: a bar pokes through the level and closes back inside the prior day's range, and you trade back the other way, expecting the level to hold.
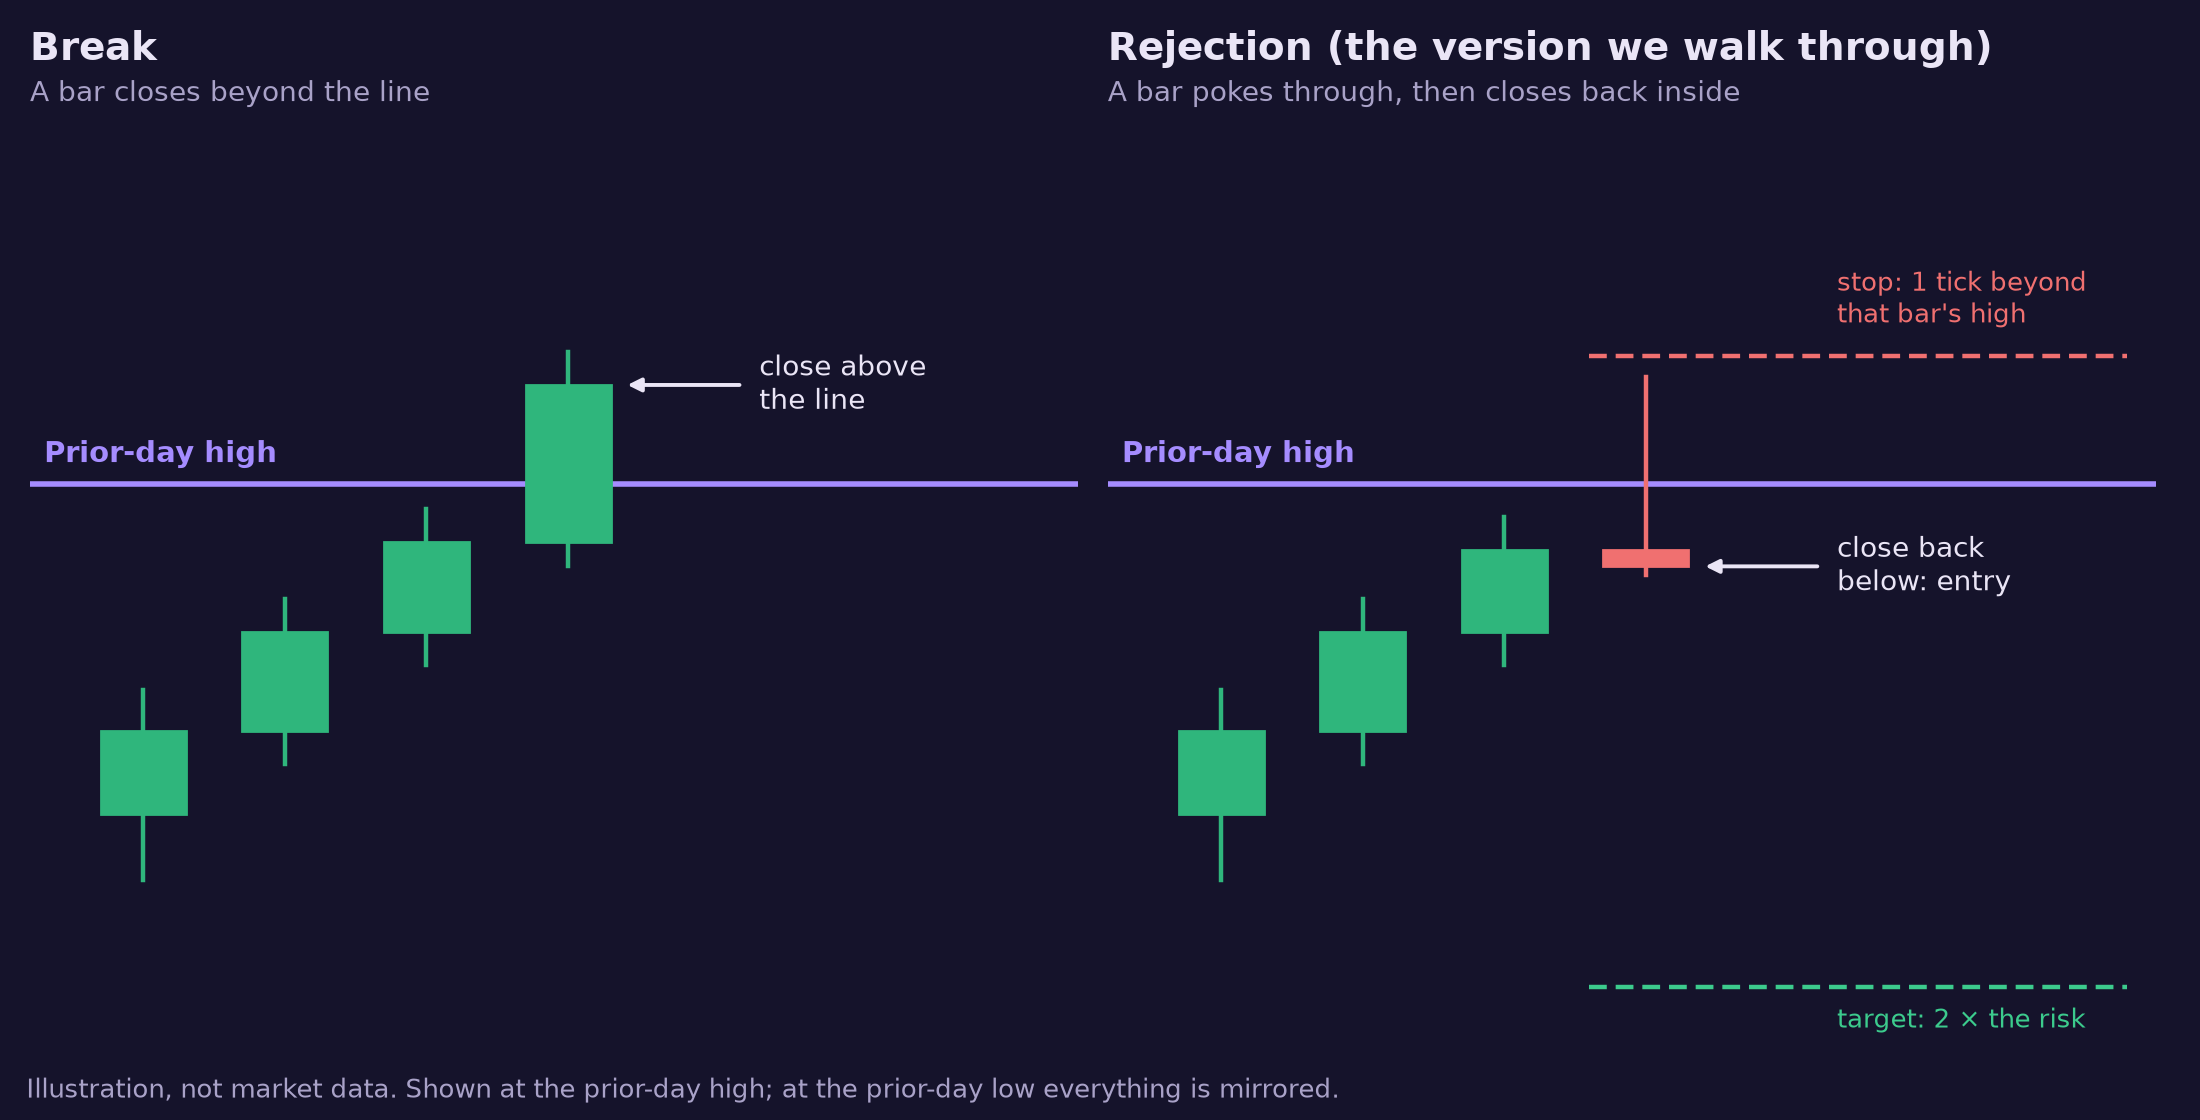
They are opposite trades on the same line, so each needs its own rules and its own test. We walk through the rejection, taught as a worked example of the rules; that is not evidence it is profitable.
The idea in five lines
- Levels: yesterday's regular-session high and low.
- Signal: a 1-minute bar that opens inside yesterday's range, trades through one of the levels and closes back inside.
- Entry: at that bar's close, back toward the middle (short at the high, long at the low).
- Stop: one tick beyond that bar's extreme.
- Exit: two times the risk, a set time of day, or the stop, and one trade a day.
Why it is tricky inside a prop account
The stop is set by one bar's wick, so its size swings from day to day: on our recorded MNQ sessions it ran from a few points to
more than 70, with the middle of that spread near 14. Small stops cause two problems. First, costs: a point of slippage on each
fill is a large share of a 10-point risk. Second, size: a small stop tempts a big position, so a "small" stop can still be a big
loss in dollars. Large stops cause the usual one: a fixed size quietly risks more. On the two MNQ sessions in the full breakdown the stops were 13.75 and 9.75 points,
$27.50 and $19.50 per micro contract before costs.
What is in the full breakdown
- The rule cardExact levels, signal, entry, stop, target, time and size rules, written so you could code them.
- A real session where it workedMNQ, 23 Sep 2026, a rejection at the prior-day low, step by step.
- A real session where it failedMNQ, 5 Oct 2026, a rejection at the prior-day high that turned into a breakout.
- Costs and sizeWhat slippage does to a 10-point stop, and how to size it under a daily loss limit.
- A test-it-yourself planHow to backtest both versions before they cost you an evaluation.
The full breakdown · free with your email
Prior-day high/low: rules, real charts, prop-rule fit
Preview below. Unlock it at the top of the page ↑ and it opens here.
1. The rule card
Prior-day high/low rejection, 1-minute bars
- Levels. The highest high and lowest low of the previous regular session,
9:30to16:00ET (8:30to15:00CT): the 1-minute bars from 9:30 through 15:59. Overnight trading is not part of the levels. - Signal. From the
9:30bar to the15:30bar, a 1-minute bar that opens inside yesterday's range, trades above the prior-day high (or below the prior-day low) and closes back inside. If the session opens beyond a level, wait until price is back inside before that level can give a signal. - Entry. At that bar's close: short at the prior-day high, long at the prior-day low.
- Stop. One tick (
0.25) beyond that bar's extreme: above its high for a short, below its low for a long. - Target. Two times the risk (entry to stop), measured from the entry.
- One trade a day. The first signal at either level is the only trade. After a stop or a target the strategy is done for the day, even if price comes back to a level.
- Time exit. If neither the stop nor the target is reached, exit at
15:50ET. - Size, with costs. Contracts = the money you allow per trade ÷ ((stop in points + your cost allowance in points) × the contract's point value), rounded down. If one contract is already more than you allow, there is no trade.
Rule 8 includes costs because the stop is often small: on a 10-point stop, two points of slippage across the entry and the
exit add a fifth to the risk. Point values come from CME Group's contract specs: MNQ is $2 a point, NQ
$20. Our examples use micros.
2. A session where the rules worked
Real chartSelected example, chosen to show the rulesTarget reached
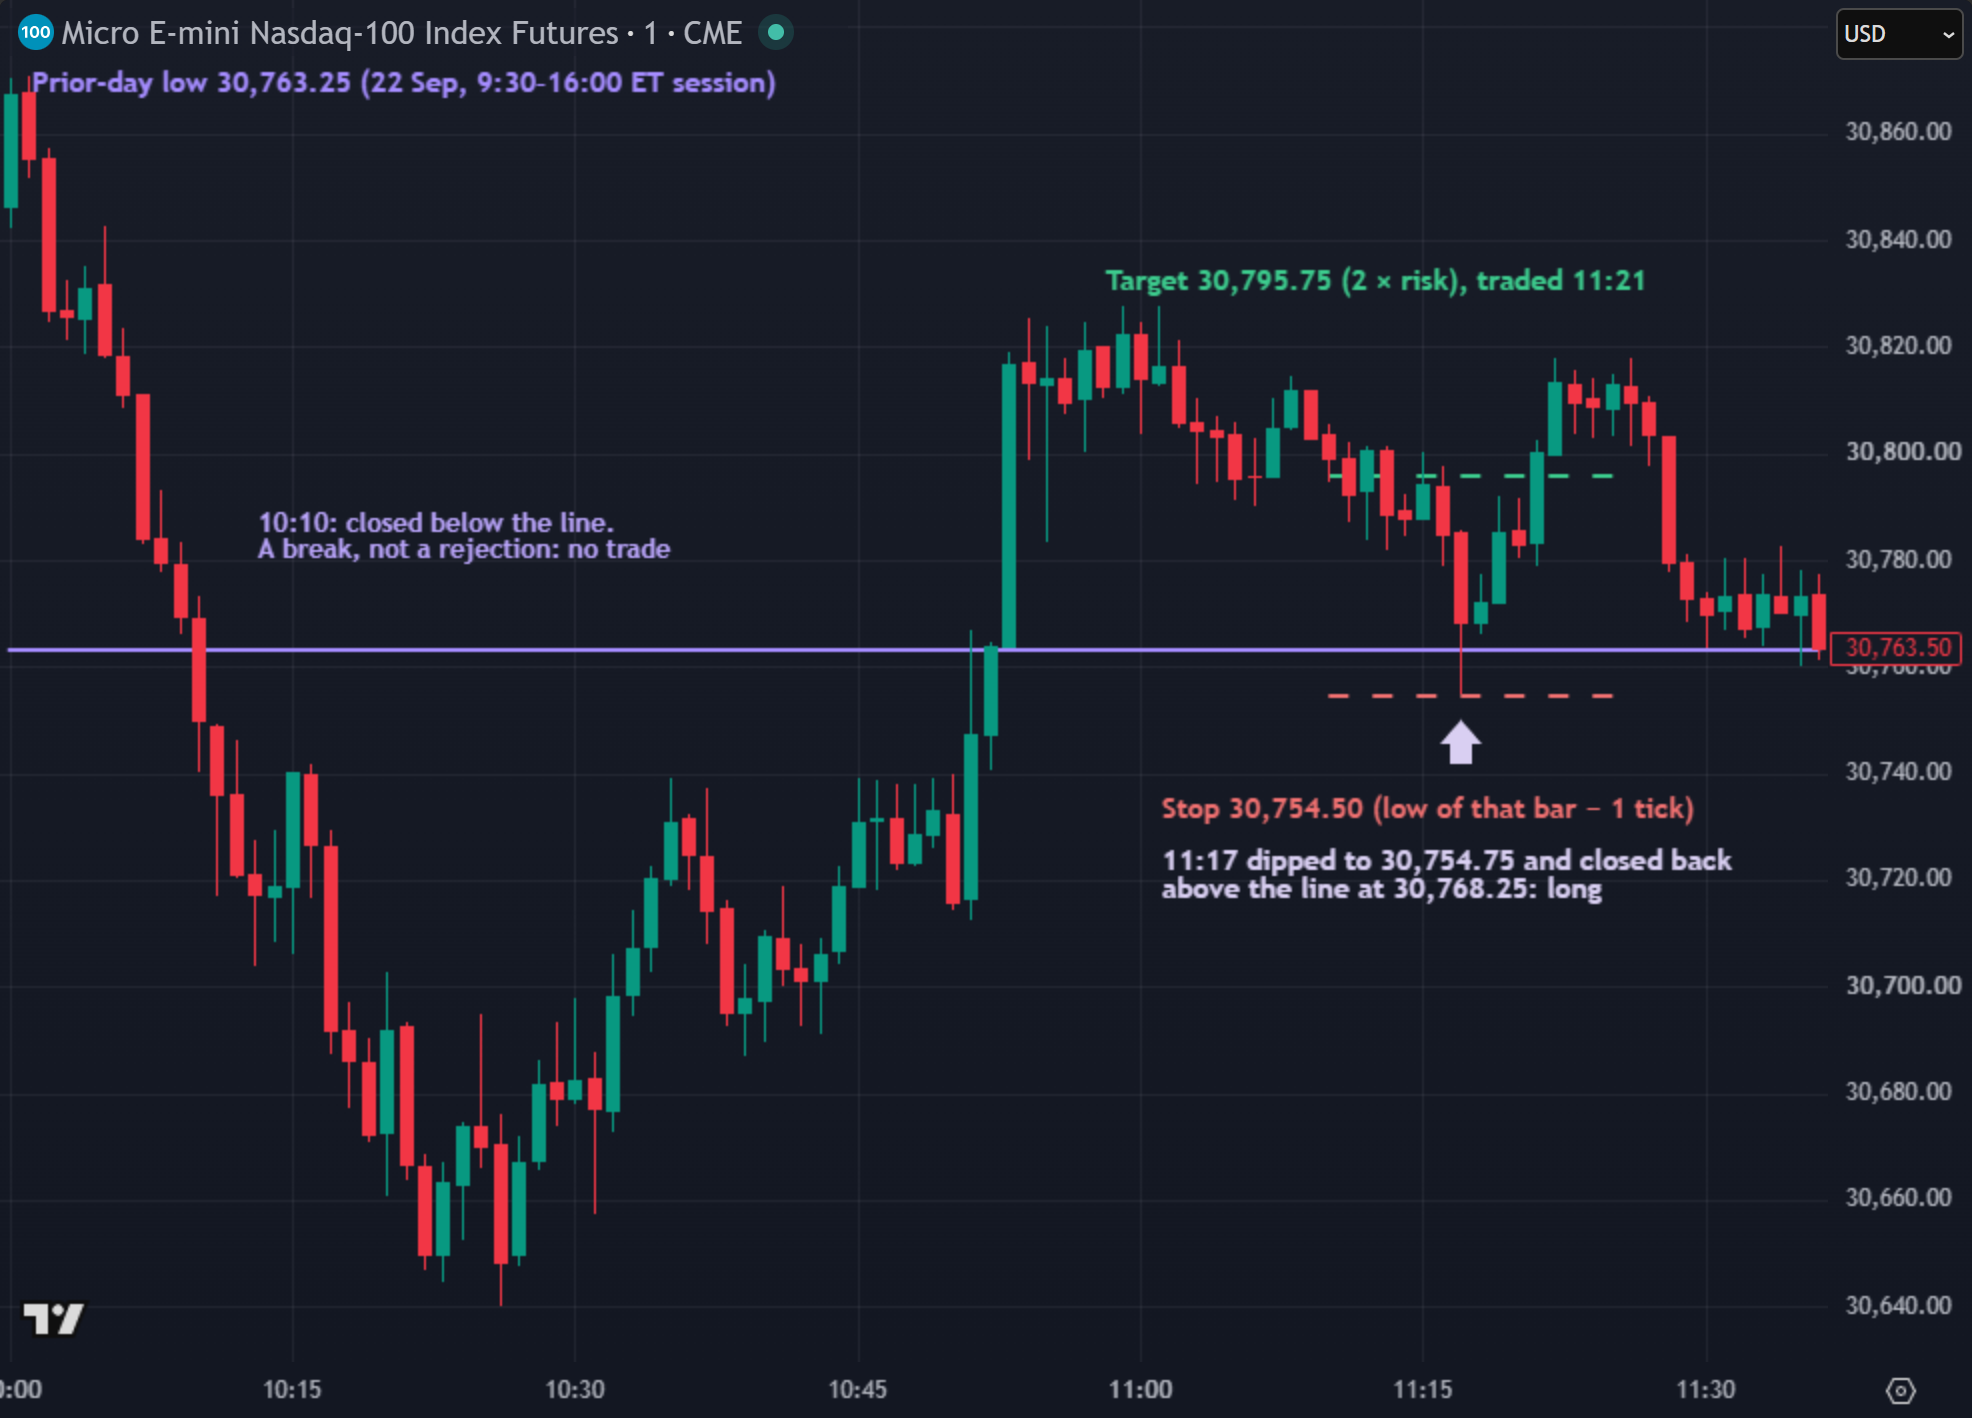
| Step | What the chart shows | Number |
|---|---|---|
| Levels | 22 Sep regular session: high at 15:53, low at 9:30 | 31,066.00 / 30,763.25 |
| No signal | 10:10: the bar opened above the low but closed below it, a break, not a rejection | close 30,750.00 |
| Signal + entry | 11:17: opened above the low, dipped to 30,754.75, closed back above. Long at the close | 30,768.25 |
| Stop | One tick below that bar's low | 30,754.50, 13.75 pts away |
| Target | Entry + 2 × 13.75 | 30,795.75, 27.5 pts away |
| Outcome | Target traded at 11:21 | risk 13.75 × $2 = $27.50, reward 27.5 × $2 = $55 per MNQ |
Read the chart from left to right. Price broke below the prior-day low at 10:10 and fell more than 100 points, which the card
ignores: a close through the line is a break, and this card only trades rejections. By 10:52 price had closed back above the line (from below, so not a signal either). At
11:17 a bar dipped through it again and closed back above; that close is the entry, and the stop sits one tick under the bar's
low. The lowest price after the entry was 30,766.25, two points under the entry, and the target traded four minutes
later. Dollar figures are per micro contract, before commissions and slippage. Hypothetical: what the written rules would have
done that day, not a trade anyone placed (CFTC Rule 4.41 notice below the next example).
3. A session where the same rules failed
Real chartSelected example, chosen to show the rulesStopped out
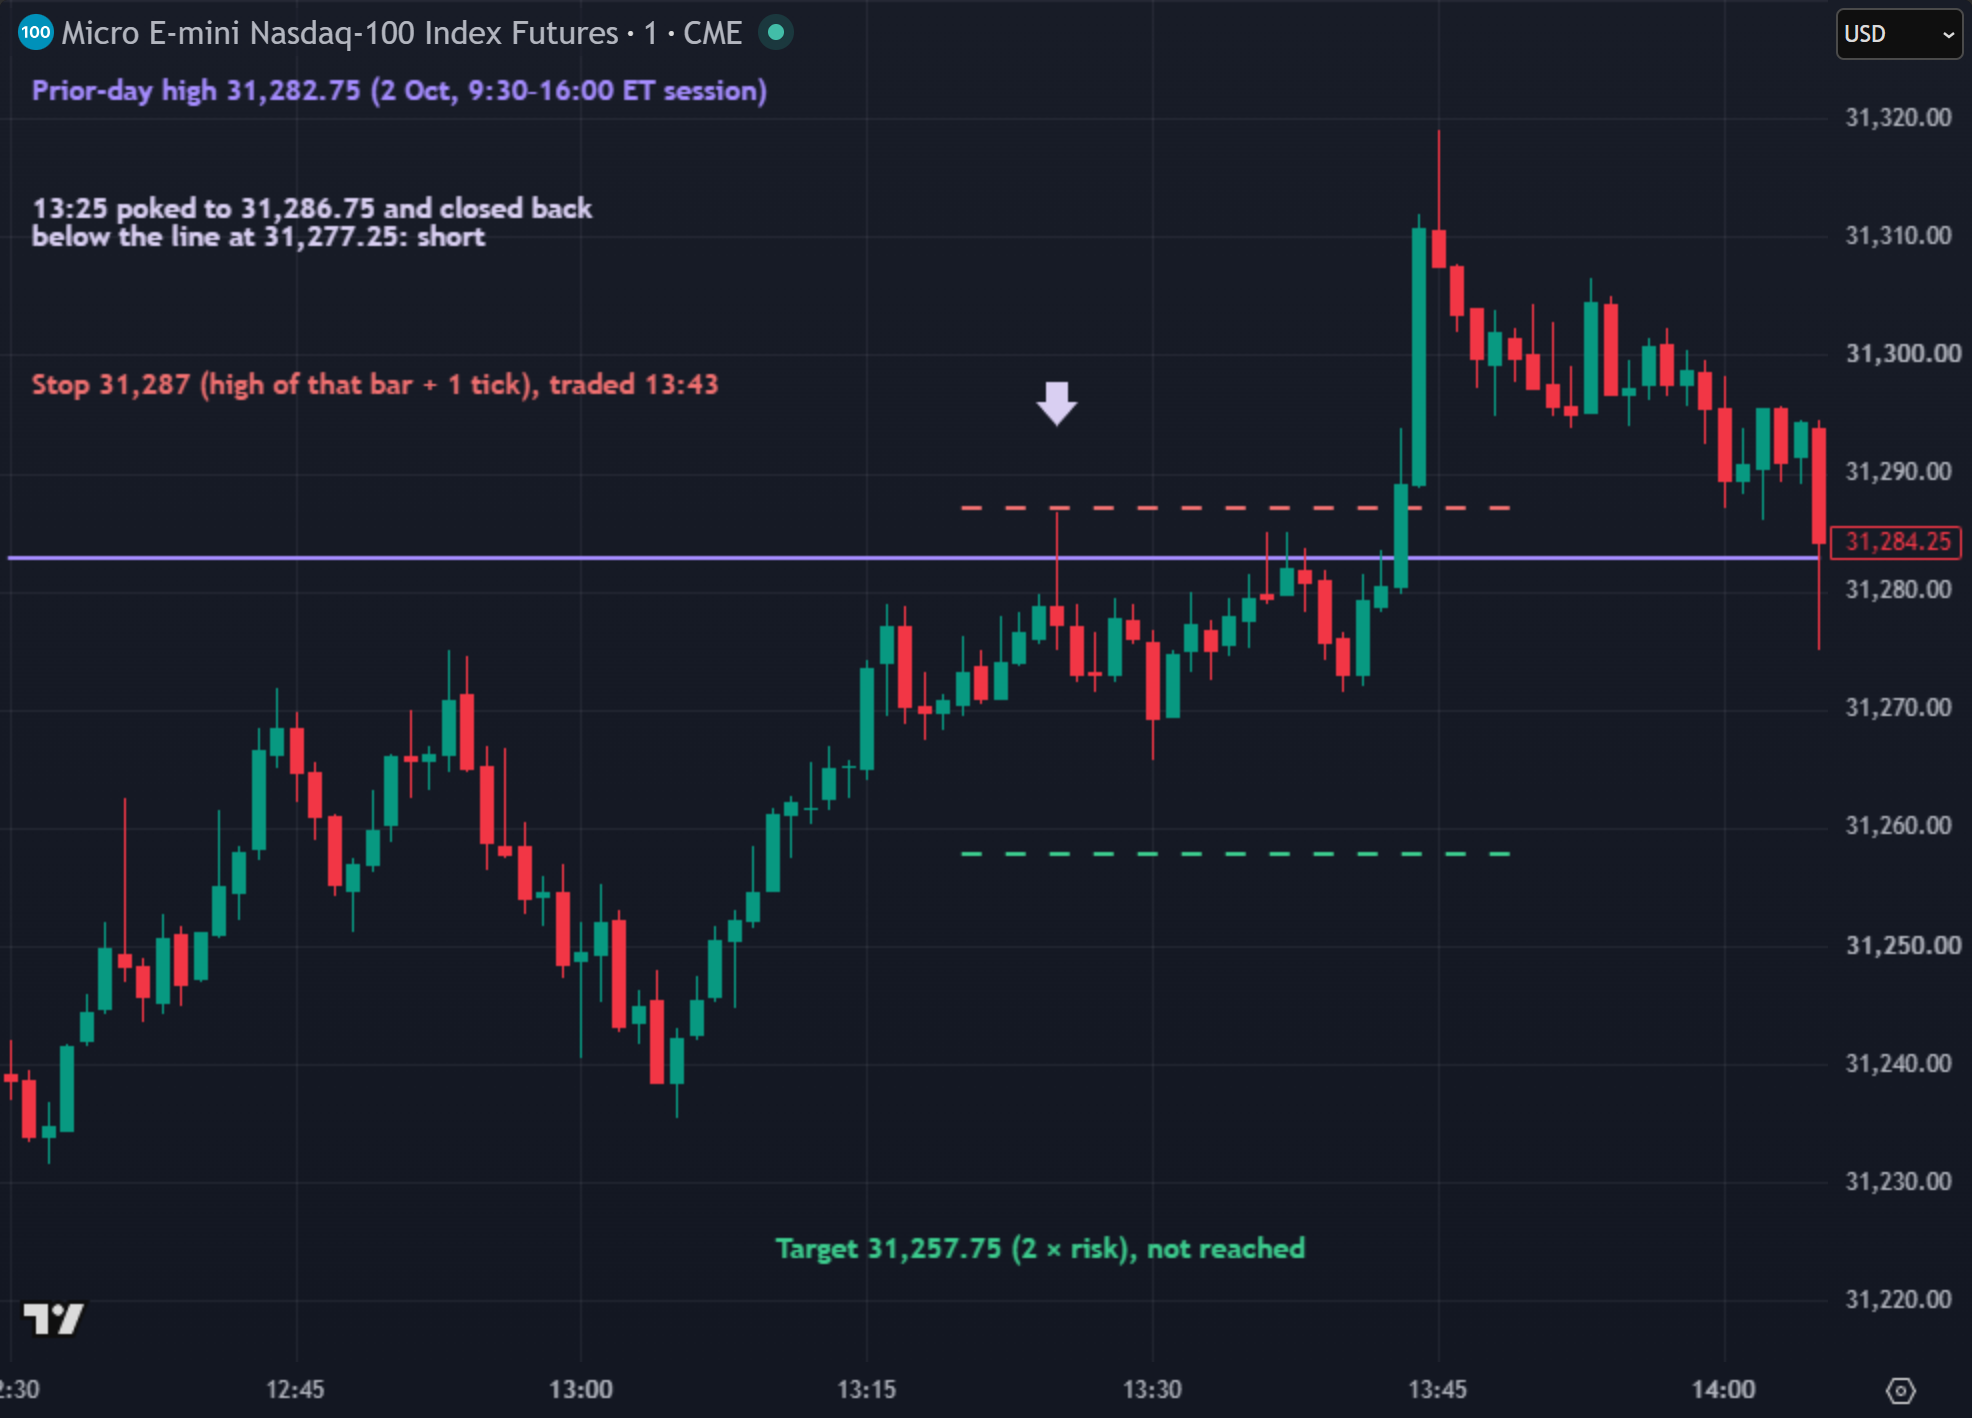
| Step | What the chart shows | Number |
|---|---|---|
| Levels | 2 Oct regular session: high at 10:27, low at 11:25 | 31,282.75 / 30,988.00 |
| Signal + entry | 13:25: the first bar of the day through either level. Poked to 31,286.75, closed back below. Short at the close | 31,277.25 |
| Stop | One tick above that bar's high | 31,287.00, 9.75 pts away |
| Target | Entry − 2 × 9.75 | 31,257.75, 19.5 pts away |
| Outcome | Best price after entry 31,265.75 (13:30), 8 pts short of the target; then price climbed through the level and the stop traded at 13:43 | 9.75 × $2 = −$19.50 per MNQ |
The stop was under ten points, so the loss per micro was small. The danger is what a small stop does to size. A trader who
thought "it is only ten points" and traded 30 MNQ would have risked 30 × $19.50 = $585 before costs.
Add an example cost allowance of one point of slippage on each fill (2 points a round trip): the loss becomes
30 × (9.75 + 2) × $2 = $705, most of a $1,000 daily loss limit (example figures) on one trade.
Sized from rule 8 with $250 a trade and the same allowance, 5 October allowed $250 ÷ ((9.75 + 2) × $2) = 10.6,
rounded down to 10 MNQ: a $235 loss including the example costs, with $765 of the example
limit left. The costs alone were $40 of that: about a fifth on top of the $195 the stop itself cost.
Rule 6 did its job too. After the stop, price ran on to 31,319 within two minutes, and the card allowed no second
trade and no flip into the breakout. Whether a flip would have helped is a question only a test on many sessions answers;
a rejection that "turns into a breakout" is a second strategy, not a rescue for the first.
Can you tell a 5 October in advance? Traders propose many tells: the time of day, how fast price arrived at the level, the volume at the touch. We have not tested any of them as a filter and do not offer one. Test any filter before trusting it.
CFTC Rule 4.41: Hypothetical or simulated performance results have certain limitations. Unlike an actual performance record, simulated results do not represent actual trading. Also, since the trades have not been executed, the results may have under- or over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profit or losses similar to those shown.
4. How it fits prop firm rules
Daily loss limit: size from the stop plus costs
Decide how many full stops you want to survive in a day, then divide. Example figures: a $1,000 daily limit and
four stops gives $250 a trade. With a 2-point cost allowance, 23 September (13.75-point stop)
is $250 ÷ ((13.75 + 2) × $2) = 7.9, so 7 MNQ; 5 October (9.75 points) is 10 MNQ.
Because the stop comes from one bar's wick, it can also be very wide; on those days the same budget allows few contracts or none.
Trailing drawdown: check the room, not the account
These trades were short: four minutes on 23 September, eighteen on 5 October. Short holds give open profit less time to lift an
intraday trailing floor, but a target day still raises your balance high, and the floor follows it. Example figures, not results:
at 7 MNQ, the 23 September target was 7 × $55 = $385 before costs; under an intraday trailing drawdown
that raises the floor up to $385 as well. Check stop × size against the room you have after the floor has trailed.
Consistency rule: one trade a day keeps days similar
With a fixed 2 × risk target and one trade a day, a target day is about twice a stop day at the same size, but the stop size
changes daily, so the dollar size of a "best day" does too. Example figures: a $385 best day under a 50%
consistency rule needs total profit of at least $385 ÷ 0.50 = $770 before it fits. Rules and percentages differ by
firm; check yours.
Close-out time
The card's 15:50 ET exit is ours. Many firms set their own time by which positions must be flat; if yours is
earlier, it becomes the time exit, and the last entry time should move with it. Check your firm's current rulebook.
5. Test it yourself before you trade it
- Write the card down exactly. Which session sets the levels (regular or overnight), time zone, bar size, "closes back inside" (not "touches"), what happens on a gap beyond a level, the stop and the tick it adds, the target, the last entry time, the time exit and one trade a day. If two people could code it differently, it is not finished.
- Test the break and the rejection separately. They are opposite trades on the same line. Do not mix them in one backtest and do not switch between them after seeing the day.
- Count the days with no signal. Many sessions never reach either level. Know how often, so a quiet week does not tempt you to loosen the rules.
- Add costs, then add more. Commission both ways and slippage on every fill, more on stops in fast markets. A delayed fill is never better than the backtest price. With stops this small, costs can decide the result on their own.
- Run your size through the rules. Longest losing streak × risk per trade against your daily limit and your trailing drawdown, then forward-test on a simulator for weeks before any paid evaluation.
Know a trader learning this strategy? Send them this breakdown. It's free for them too.
Disclosures
Education only. This page explains how a widely known, public strategy is defined and how you could test it yourself. It is not advice, not a recommendation to trade any contract, size or strategy, and not a signal: it shows no setup for any future session. Charts are real past sessions, chosen to show the rules (including a day they failed); they are selected examples, not typical results. The charts are TradingView snapshots (MNQ1!, regular trading hours, one-minute unless the caption says otherwise); diagrams labelled as illustrations are drawn by Tarrow Futures and are not market data. The level, range, entry, stop and target marks and labels on them were added by Tarrow Futures. Bars may differ slightly from those on your platform. Trade outcomes on this page are what the written rules would have done on those days, before commissions and slippage. They are not trades Tarrow Futures placed. Dollar figures for sequences and rules are example figures, not results. Prop firm rules differ and change; your firm's current rulebook decides. Futures trading involves substantial risk of loss. Automation does not remove risk.
CFTC Rule 4.41: Hypothetical or simulated performance results have certain limitations. Unlike an actual performance record, simulated results do not represent actual trading. Also, since the trades have not been executed, the results may have under- or over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profit or losses similar to those shown.