Home / Blog / Strategy Testing & Automation
Strategy Testing & Automation
What is the initial balance breakout strategy?
The initial balance is the high and low of the first hour of the session. An initial balance breakout waits for that hour to finish, then enters when price closes outside it, in the direction of the break, with the stop inside the range. It is one of the simplest initial balance trading strategies to write down exactly, which is also what makes it testable.
This post defines each part as a number, walks through a real MNQ session, and shows why the stop size decides whether the strategy fits a prop account with a daily loss limit and a trailing drawdown.
The initial balance, defined
The term comes from Market Profile, the way of reading price and time developed at the Chicago Board of Trade in the 1980s. The first hour was treated as the session's opening auction: the range the market settled on before the rest of the day was traded against it.
For US index futures (MNQ, NQ, MES, ES), the first hour almost always means the cash session, 9:30 to 10:30 ET (8:30 to 9:30 CT). The futures trade nearly around the clock, but that is when volume and range jump.
| Term | Meaning |
|---|---|
| Initial balance (IB) | High and low from 9:30 to 10:30 ET |
| IB high / IB low | The two edges a breakout is measured from |
| IB midpoint | (high + low) ÷ 2, a common stop for the breakout |
| IB extension | A move beyond the IB, often measured in multiples of its width |
Compared with an opening range breakout, the window is longer: an hour instead of 5, 15 or 30 minutes. That means fewer signals, later entries and wider stops.
The rules, as a checklist
The version we walk through, on 1-minute bars:
- Initial balance: the high and low from
9:30to10:30ET. - Entry: from the
10:30bar on, the first 1-minute bar that closes outside the range. A wick through the line is not a break. No new entry after15:30ET. - Stop: the middle of the range, rounded to the next
0.25tick away from the entry. - Target:
2 ×the risk, measured from the entry. - One trade a day, and flat at
15:50ET if neither stop nor target is reached. - Size: contracts = money allowed per trade ÷ (stop in points × point value), rounded down.
We also tested a version that waits for price to come back and retest the broken level before entering. On our recorded MNQ sessions its tight stops were chopped up, so it is not the version we teach. That is one small sample, not a verdict on retests; test your own. We teach the plain breakout as a worked example of the rules; that is not evidence it is profitable.
A worked example on a real MNQ session
Real chart, past session, selected to show the rules (not a typical result). MNQ1!, 1-minute, 5 August 2026; chart: TradingView snapshot, levels and labels marked by Tarrow Futures.
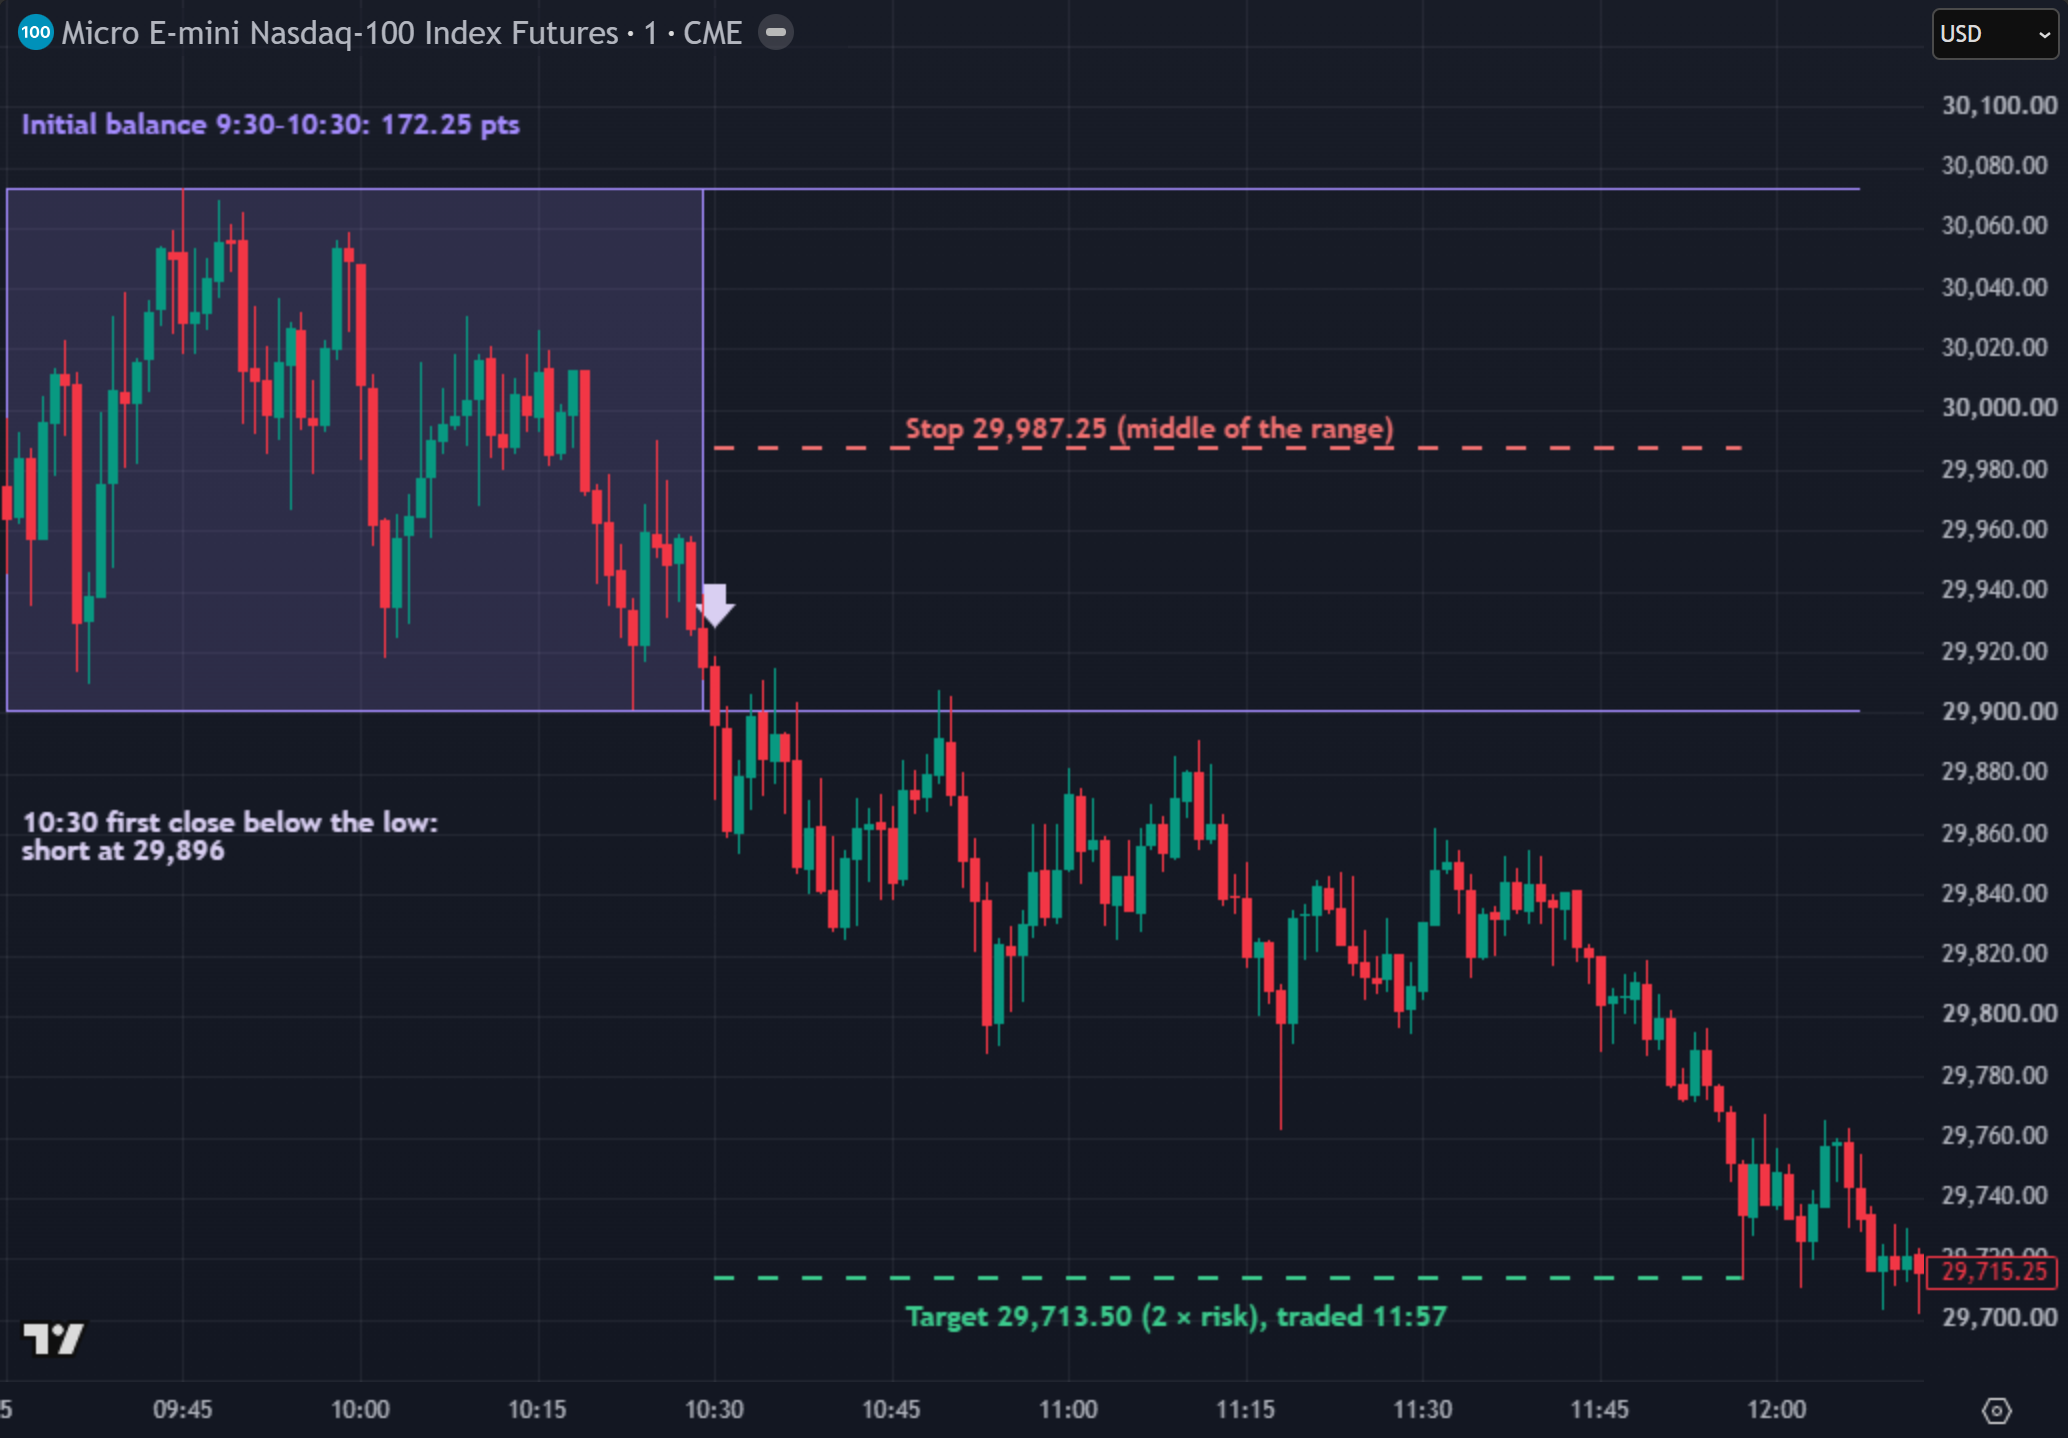
- The first hour,
9:30to10:30ET, ran from29,901.00to30,073.25:172.25points. - The
10:30bar closed below the range at29,896.00. That close is the entry (short). - The middle of the range is
29,987.125; rounded up a tick, the stop is29,987.25:91.25points of risk. - The target is the entry minus
2 × 91.25,29,713.50:182.5points away. It traded at11:57.
MNQ is $2 a point (CME Group contract specs), so per micro contract that is 91.25 × $2 = $182.50 of risk and 182.5 × $2 = $365 of target, before commissions and slippage. Hypothetical: that is what the written rules would have done that day. It is not a trade we placed, and other sessions went differently, including the one in the next section.
Why the first hour's width is your risk
On another real MNQ session, 1 October 2026 (also selected to show the rules, not a typical result), the first hour was 296.25 points wide and the same rules stopped out. The first close outside the range came at 11:08, short; the break went 27.25 points further, then price climbed back through the middle of the range and the stop traded at 13:19. The stop was 149.5 points from the entry, or $299 per micro: about 1.6 times the risk of 5 August, with exactly the same rules.
| 5 Aug | 1 Oct | |
|---|---|---|
| First-hour width | 172.25 pts |
296.25 pts |
| Stop distance | 91.25 pts |
149.5 pts |
| Risk per MNQ | $182.50 |
$299 |
Risk at a fixed 3 MNQ |
$547.50 |
$897 |
MNQ from a $500 budget |
2 |
1 |
At a fixed 3 contracts, one losing trade on 1 October uses almost all of a $1,000 daily loss limit (example limit). Sized from the stop with a $500 budget, it is one contract and a $299 loss. On NQ, at $20 a point, the same stop was $2,990 for one contract. The full breakdown walks through that failed session on the chart.
Hypothetical results. The outcomes above are what the written rules would have done on selected past sessions, before commissions and slippage; they are not trades anyone placed. CFTC Rule 4.41: hypothetical or simulated performance results have certain limitations. Unlike an actual performance record, simulated results do not represent actual trading. Also, since the trades have not been executed, the results may have under- or over-compensated for the impact, if any, of certain market factors, such as lack of liquidity. Simulated trading programs in general are also subject to the fact that they are designed with the benefit of hindsight. No representation is being made that any account will or is likely to achieve profit or losses similar to those shown.
How the initial balance breakout fits prop firm rules
- Daily loss limit. Decide how many stops you want to survive, divide your daily budget by that, then divide by the cost of one stop. With a mid-range stop on a full hour's range, some days one micro is already too much; on those days the rule is no trade. The position size calculator does the division for your own numbers.
- Trailing drawdown. The trade starts at
10:30or later and can stay open into the afternoon. Under an intraday trailing drawdown, open profit lifts the floor while it is open. Example figures, not results: at2MNQ, a trade that runs to+$600open and reverses to a$365stop shrinks your room by$965, not$365. - Consistency. With a 2 × risk target and one trade a day, a target day is twice a stop day. Under a 50% rule (example), a
$730best day needs$1,460of total profit before it fits. Rules and percentages differ by firm; check yours with the consistency rule checker. - Close-out time. Many firms require you to be flat by a set time. If yours is earlier than the card's time exit, it becomes the time exit.
Common mistakes
- Entering on the touch, not the close. A wick through the IB high and a close above it are different signals with different results.
- Fixed size, variable range. The first hour moves your risk every day unless the size moves the other way.
- Ignoring the time exit. With a target this far away, some days end with neither level reached. Count those days in your test; they are part of the strategy.
- Testing without costs. Breakouts fill in fast markets. Add commission both ways and slippage on every fill; a late fill is never better than the backtest price.
- Adding a filter from a handful of days. "Only trade narrow first hours" may sound right, but if it was not tested on many sessions, it is a story, not a filter.
Test it before you trade it
Write the rules so two people would code them the same way, backtest them on your contract over many sessions with costs, run your size through your firm's daily limit and trailing drawdown, then forward-test on a simulator. Our free guide, Build It, Break It, Then Trade It, walks through each step.
The full initial balance breakout breakdown has the rule card, both real MNQ sessions step by step (the target and the stop), and the prop-rule arithmetic in one place. It is free with your email, below.
Charts are TradingView snapshots of past sessions; the levels and labels on them were added by Tarrow Futures. Trade outcomes shown are hypothetical; see the CFTC Rule 4.41 notice after the examples above.
Free strategy breakdown · free with your email
Initial balance breakout breakdown
The rule card, two real MNQ sessions (one target, one stop) and how to size a stop that is half the first hour's range. We email you the link, so it is one tap away next time.
✓ It's yours. The link is on its way to your inbox. Open the initial balance breakout breakdown now
Read the free overview firstQuestions
What is the initial balance in trading?
The high and low of the first hour of the trading session. The term comes from Market Profile. For US index futures it usually means 9:30 to 10:30 ET (8:30 to 9:30 CT), the first hour of the cash session.
How does an initial balance breakout work?
You wait for the first hour to finish, then enter when a bar closes outside its high or low, in the direction of the break. The stop goes inside the range (often the middle) and the exit is a multiple of the risk, an extension of the range, or a set time of day.
What is the difference between an initial balance breakout and an opening range breakout?
The window. An opening range is usually the first 5, 15 or 30 minutes; the initial balance is the first full hour. The longer window gives fewer signals, later entries and wider stops, so sizing matters even more.
What is an initial balance extension?
A move beyond the initial balance, often measured in multiples of its width, such as 1.5 or 2 times the range. Some traders use extensions as targets. They are reference levels, not predictions; test any target on your own contract before trusting it.
How many contracts should I trade on an initial balance breakout?
Size from the stop, not the account. Contracts = the money you allow per trade ÷ (stop distance in points × the contract's point value), rounded down. If one contract already risks more than you allow, there is no trade that day.
Educational material only. Not financial, investment or trading advice, and not a recommendation to trade any contract or size. Prop firm rules differ and change; the current rulebook of the firm you use decides. Worked examples use example figures, not results. Futures trading involves substantial risk of loss. Evaluations are paid tests and most people who take one do not pass.